

The short version
|
CSRD reporting happens at group level. ESRS E5 asks for tonnes of food waste by stream and by treatment route, plus a statement of whether the data is measured or estimated. It does not require ingredient-level identification, and it does not require site-level disclosure.
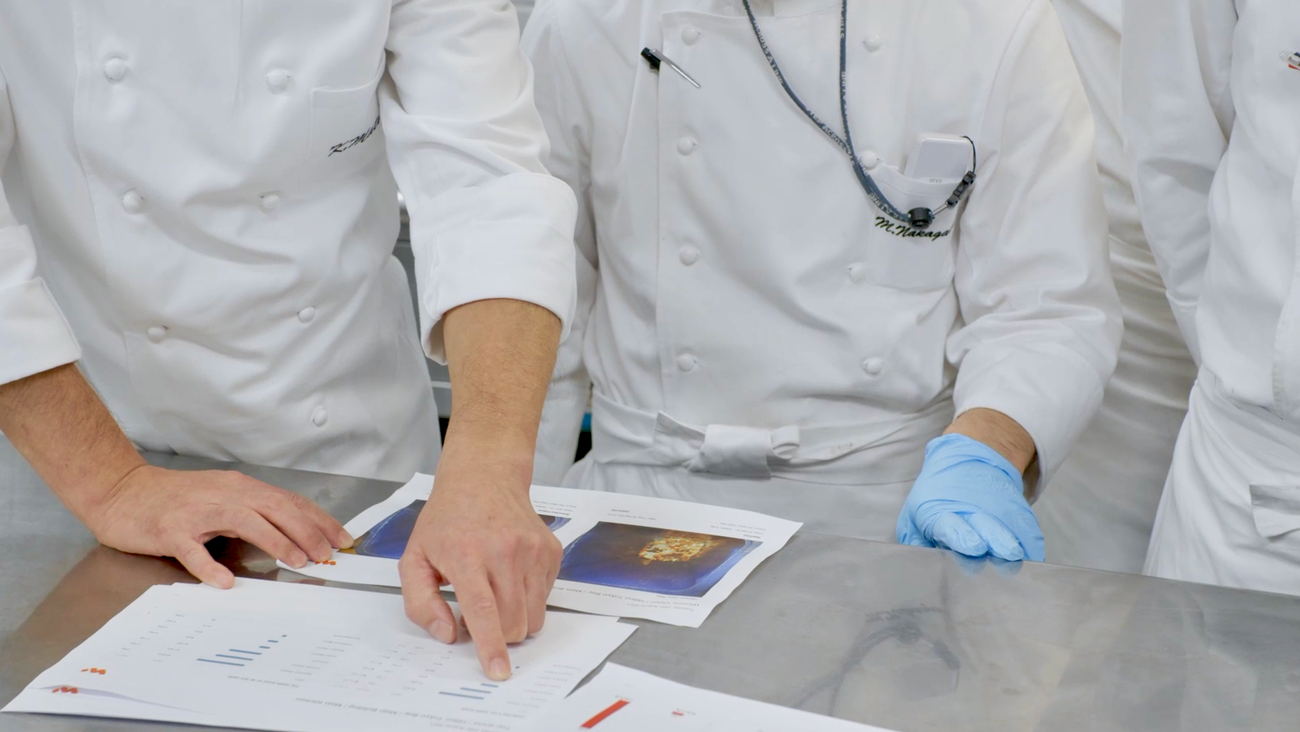
The strongest position with auditors is direct measurement at source. Winnow delivers auditable, CSRD-ready food waste data: each disposal into the measured waste bin is weighed on a connected scale, timestamped and photographed, captured the same way in every kitchen, and exportable for your disclosure.
The Omnibus directive, in force since March 2026, narrowed CSRD to companies with more than 1,000 employees and 450 million euros turnover. Guides still quoting the 500-employee threshold are out of date.
One thing no bin technology gives you on its own: the landfill, incineration and donation split. That comes from your waste contractor. Anyone telling you their camera alone makes you CSRD-ready is skipping this part. |
Who this guide is for
This is written for sustainability leads, finance directors and F&B leaders at hotel groups and contract caterers who need to report food waste under the EU Corporate Sustainability Reporting Directive (CSRD) and its European Sustainability Reporting Standards (ESRS). If you are being asked whether your food waste data will "pass an audit", this guide explains what the regulation actually requires and how measured kitchen data fits in.
Does CSRD require ingredient-level food waste data?
No. The relevant standard, ESRS E5-5 on resource outflows, requires food waste in tonnes by waste stream and treatment route, plus a disclosure of the methodology used. It does not require identifying individual ingredients. Ingredient-level detail is operationally useful for cutting waste, and systems like Winnow provide food-category detail for exactly that reason, but it is not what the regulation asks for. No vendor's ingredient count changes your compliance position.
Is site-level food waste and CO2e data enough for ESRS E5?
Yes, and it is more than the disclosure strictly requires. CSRD disclosures are made at the level of the consolidated reporting company, not the individual site. Food waste emissions sit in your Scope 3 inventory under ESRS E1, calculated using the GHG Protocol from measured tonnage. Site-level tonnage and estimated CO2e are inputs your group aggregates upward, so reporting them at site level is more granular than the standard demands, not less. What an assurance provider examines is whether the underlying tonnage was measured rather than assumed, and whether the emission factors and method are documented and applied consistently.
Measured or estimated: the one question that decides your disclosure
ESRS E5 asks one question that decides how your food waste disclosure holds up: is the data measured or estimated? Paragraph 40 of disclosure requirement E5-5 requires you to say which, in writing, in an audited statement, and to disclose your key assumptions. Estimates built from contractor invoices and conversion factors get challenged in assurance. Measured data with a documented method passes.
Winnow answers that question plainly. Each disposal into the measured waste bin is weighed on a connected scale, timestamped at the moment it happens, and photographed. The photograph is the part that matters in an assurance review. It is independent evidence that the recorded weight corresponds to real food waste, captured the same way in every kitchen, on every service, across 94 countries. There is no manual log to abandon mid-service, and no method that changes when staff change.
Not every system works this way. Some record transactions without an image at all. We think the standard should be simple: if it went in the measured bin, there is a picture of it.
What makes food waste data audit-ready?
An assurance provider is not looking for a dashboard. They are looking for evidence they can test. Four properties make measured kitchen data audit-ready, and they are the properties Winnow data has:
- Measured, not estimated. Every disposal in the measured waste receptacle is weighed on a connected scale, so the figures sit in the direct-measurement category ESRS E5-5 paragraph 40 treats most favourably.
- Evidenced. Every scale-weighed disposal carries a timestamp and a photograph. That is the audit trail behind the number: independent evidence that what was recorded is real food waste.
- Consistent and documented. The same capture method runs in every kitchen and every service, with a documented methodology. Auditors test two things, whether the data was measured and whether the method is documented and applied consistently. Measured kitchen data can satisfy both.
- Mappable and exportable. The data is available in Winnow Hub by site, service and food category, with cost and aggregated estimated CO2e attached. Transactions can be downloaded by date range, so the evidence can be handed to an auditor and dropped into your disclosure workpapers, not just viewed on screen.
What food waste data can no kitchen system provide for CSRD?
The breakdown of waste directed to disposal by treatment type: landfill, incineration and other routes, plus recovery routes like composting and donation. This is determined after collection and comes from your waste contractors and donation partners. No camera above or inside a bin generates it. A measurement system gives you the accurate tonnage that this split is applied to. Any system claiming its camera alone makes you CSRD-ready is overlooking this requirement, and it is worth asking a prospective vendor directly how they intend to source it.
Did the 2026 Omnibus directive change who has to report?
Yes. The Omnibus directive, Directive (EU) 2026/470, entered into force on 18 March 2026. It narrows mandatory CSRD scope to companies with more than 1,000 employees and net turnover above 450 million euros, removes listed small and medium enterprises from scope, and introduces a simplified set of ESRS. The CSRD amendments apply to financial years starting from 1 January 2027, with the first reports due in 2028.
What this means in practice: fewer mid-size hospitality groups are in mandatory scope than earlier guides imply, but large hotel and catering groups remain squarely in scope. Brand standards, franchise requirements and investor expectations also keep voluntary reporting alive well below the legal threshold, so the demand for defensible food waste data has not gone away.
What about binding food waste reduction targets?
Separately from CSRD, the revised Waste Framework Directive, Directive (EU) 2025/1892, has been in force since 16 October 2025. It sets the first binding EU food waste reduction targets: a 30% per capita reduction across retail, distribution, restaurants, food service and households, and a 10% reduction in processing and manufacturing, both by 31 December 2030 against a 2021 to 2023 baseline. The legal obligation sits on Member States, which must adapt their national waste prevention programmes; it does not fall directly on individual operators yet. But national measures will flow down, and you cannot show a reduction against a baseline you never measured. A stable, consistent measurement method matters here: a target is only credible against a baseline built the same way year on year. National laws such as France's Loi Garot and Italy's Gadda Law already apply regardless of CSRD scope.
How measured kitchen data maps to each reporting framework
This table is the practical reference. It shows what a measurement system covers, and, honestly, what it does not.
|
Framework and datapoint |
What measured kitchen data provides |
Where the data must come from elsewhere |
|---|---|---|
|
CSRD / ESRS E5-5, food waste in tonnes |
Measured tonnage by site and period, with methodology documentation for the paragraph 40 direct-measurement disclosure |
Landfill, incineration and donation split, from your waste contractor |
|
ESRS E1 / GHG Protocol Scope 3 |
Measured tonnage as activity data, with CO2e factors applied consistently across sites |
Group-level Scope 3 consolidation |
|
GRI 306 (Waste) |
Measured food waste tonnage, weighed and image-verified per throw, with methodology documentation for the GRI 306-3 disclosure |
Downstream waste disposal method, sourced by the customer |
|
SASB FB-RN-150a.1 |
Total waste and food waste percentage from measured site-level data |
— |
|
National laws (e.g. Loi Garot, Gadda Law, Directive (EU) 2025/1892 programmes) |
Evidence of measurement and prevention activity against a baseline |
— |
How Winnow fits
Winnow measures food waste at source and delivers it as auditable, CSRD-ready data. Each disposal into the measured waste bin is weighed, timestamped and photographed, then available in Winnow Hub by site, service and food category, with cost and aggregated estimated CO2e attached and downloadable by date range. That gives sustainability teams measured data rather than estimates for the datapoints in the table above, backed by a decade of records captured against a consistent method, so year-on-year baselines and reduction targets rest on a method that does not change under them. Winnow is used by groups such as Hilton and IKEA. We are clear about the limit: the treatment-route split comes from your waste contractor, and Winnow gives you the measured tonnage it is applied to.
Frequently asked questions
Does Winnow data support CSRD reporting?
Yes. Winnow delivers auditable, CSRD-ready data: each disposal into the measured waste bin is weighed, timestamped and photographed. That maps to ESRS E5-5, which requires waste quantities in tonnes and a statement of whether figures come from direct measurement or estimation. Your group reports at consolidated level, and Winnow provides the measured site-level evidence underneath it, exportable from Winnow Hub by date range.
Is site-level CO2e data enough for CSRD?
Yes. CSRD disclosures are made at group level. Food waste emissions sit in Scope 3 under ESRS E1, calculated per the GHG Protocol from measured tonnage. Site-level estimated CO2e is an input your group aggregates, so it is more granular than the disclosure requires. What auditors examine is whether the tonnage was measured and the method documented.
Does CSRD require ingredient-level food waste data?
No. ESRS E5-5 requires tonnes by waste stream and treatment route plus methodology disclosure. Ingredient-level detail is operationally useful for cutting waste, and Winnow provides food-category detail for that reason, but it is not what the regulation asks for, and no vendor's ingredient count changes your compliance position.
What food waste data can no kitchen system provide for CSRD?
The breakdown of waste directed to disposal by treatment type: landfill, incineration and other routes, plus recovery routes like composting and donation. That is determined after collection and comes from waste contractors and donation partners. Any system claiming its camera alone makes you CSRD-ready is overlooking this requirement.
Is my hotel group still in scope after the 2026 Omnibus changes?
If your group has more than 1,000 employees and net turnover above 450 million euros, yes. Below that, mandatory CSRD reporting may no longer apply, but brand standards, franchise agreements, investor expectations and national food waste laws often still require credible food waste measurement.
Sources
- EFRAG, ESRS E5 Resource use and circular economy (Delegated Act annex), disclosure requirement E5-5, paragraphs 37 to 40. https://www.efrag.org/sites/default/files/sites/webpublishing/SiteAssets/ESRS%20E5%20Delegated-act-2023-5303-annex-1_en.pdf
- Council of the EU, simplification of sustainability reporting and due diligence, 24 February 2026. Directive (EU) 2026/470 (Omnibus), in force 18 March 2026.
- European Commission, Directive (EU) 2025/1892 revised Waste Framework Directive, in force 16 October 2025, food waste reduction targets for 2030.
- GHG Protocol Corporate Value Chain (Scope 3) Standard.
- GRI 306: Waste (2020), disclosure 306-3 Waste generated.
Ready to reduce food costs in your kitchen?
See how Winnow helps your kitchens produce the right amount. Kitchens worldwide trust it.